An SEO analysis of the US country wear industry
Boot Barn passed $1 billion in annual sales for the first time in its fiscal year to March 2022. According to the same SEC report, it doubled its total addressable market estimate from $20 billion to $40 billion, a clear signal that the biggest player in country wear sees plenty of room to grow.
The pandemic hit country wear differently than some other industries. When stores closed, shoppers who would normally try boots on in person moved to buying online. In a category where most sales still happen in store, organic search suddenly became the main way many of them found a retailer.
This analysis evaluates how the US country wear industry has changed in organic search since 2020. It covers how demand shifted during the pandemic, how Google updates affected the market, and how five competitors performed.
Key US country wear SEO analysis findings
Five standout points from our SEO analysis of the US country wear industry:
- Demand during the pandemic didn’t bounce back when lockdowns lifted. It recovered gradually, then hit a five-year high in December 2021.
- The November 2021 local search update caused the largest negative traffic swing of any update we measured.
- Google’s 2022 product reviews updates coincided with lifting estimated traffic for the country wear industry in our five competitor windows.
- For page experience, desktop (not mobile) was the weak spot.
- Buckle kept growing organic traffic into 2023 while most of the others plateaued, helped by a broader range and a wider set of long-tail keywords.
How country wear demand moved through the pandemic
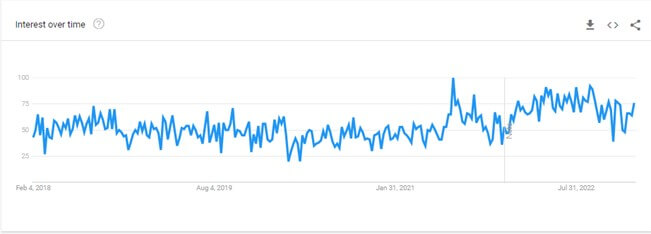
Search volume for country wear declined before March 2020, then began to recover. This shift likely occurred because most US states lifted the stay-at-home order from April to June 2020.
Country wear can mainly be categorised as outdoor wear, including cowboy boots and work pants, so the stay-at-home order played a significant role in the decline of search volume.
Here’s the counterintuitive part: we expected search volume to jump once lockdowns eased, but it didn’t. It climbed gradually instead.
Lots of country wear demand is tied to occasions like rodeos, country music concerts, festivals, weddings, and a return to job sites – not to a store reopening. Those came back slowly through late 2020 and 2021, so search volume shifts followed them rather than the store reopening dates.
That matters for SEO planning, as demand follows the calendar of events and seasons in this category. Publishing and timing content and campaigns to target those moments are likely to outperform a generic ‘we’re open’ push.
To explore the market trend more comprehensively, we looked at the search topic “cowboy boot”, as this is a product all analysed competitors offer.
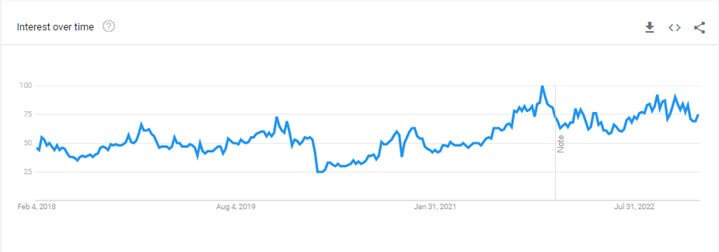
Because this topic has a higher search volume, the trend is less sporadic but follows the same pattern. We see clear seasonality, with yearly highs in December and lows in the summer. This suggests cowboy boots are often bought as Christmas gifts, which is reflected in the price range.
Boot Barn, one of the competitors we will analyse, sells cowboy boots ranging from $80 to $2,700.
The combination of expected seasonality and further relaxation of lockdown restrictions likely caused the five-year high in 2021. The timing matches Boot Barn’s results: its fiscal year to March 2022, which covers that December peak, was the year its sales rose 66.6%.
Industry-wide SEO findings
To see who captured search demand, we used Ahrefs to look at the keywords each website ranks for.
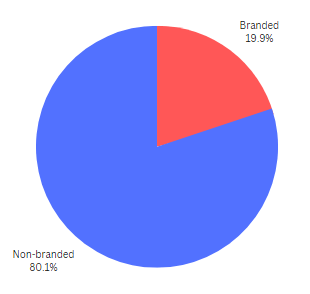
Boot Barn’s branded vs non-branded split across its top keywords points to a wide set of long-tail keywords. These indicate non-brand demand we routinely separate out when sizing up an SEO opportunity. That long-tail shape is why disciplined technical and content SEO can still move the needle in country wear, not just brand demand.
Taking a more granular look at the state of SEO in this industry, we can analyse which algorithm updates affected performance the most.
Using SALT’s internal algorithm-impact model, we compared estimated organic traffic in fixed windows before and after each rollout, adjusting for category search-volume shifts across the same five-competitor set. That separates an update’s effect from normal seasonal swings, which is important for a category that peaks every December.
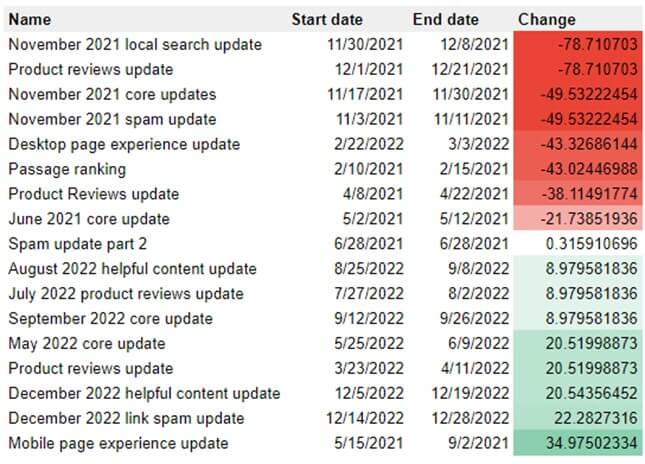
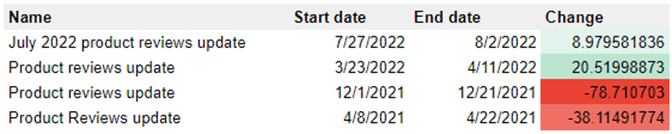
There are a few key findings from this, the first being that more recent product reviews updates have led to improvements in performance. In our windows, Google’s March, July, and September 2022 product reviews updates coincided with net positive traffic swings.
That’s likely because retailers adjusted their product content after earlier updates hit them, adding first-hand detail and comparisons that these updates reward. It shows the value of measuring updates inside one niche: the news cycle mentions an update happened, but only this analysis explains how a specific market responded.
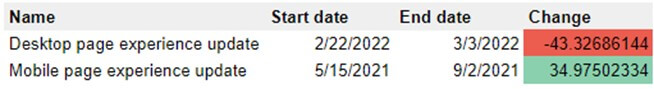
Secondly, the desktop and mobile page experience updates had very different effects. The mobile page experience update (rolled out June to August 2021) had a positive effect on this set, while the desktop update (February to March 2022) had a negative one, which was unexpected.
This suggests these retailers’ mobile experience held up better than their desktop sites. It’s therefore always worth auditing the desktop experience rather than assuming mobile is always the weak point.
Across this competitor set, the November 2021 local search update showed the largest adverse traffic swing in our model. We treat that as a sign that local intent matters disproportionately in country wear, rather than as a rule for all apparel. That’s consistent with Boot Barn reporting stores at 86% of net sales in the final quarter of fiscal 2022.
Since most country wear products are clothing and footwear, many consumers visit a physical store to try items on before buying. Boot Barn’s own results reflect this, as retail stores made up 86% of its net sales in the final quarter of fiscal 2022, and e-commerce accounted for 14%.
The customer journey during the pandemic was of course different because customers didn’t have the option to try on items. This required a shift in strategy to target new keywords, such as fit and sizing searches (to replace an in-store try-on), or change site architecture.
For multi-store retailers like Boot Barn, Cavender’s, and Buckle, local landing pages, accurate store data, and consistent business information across Google Business Profile and directories are a core part of SEO.
We now look at five competitors in the industry:
- Boot Barn
- Sheplers
- Country Outfitter
- Cavender’s
- Buckle.
One thing to bear in mind: three of these five sites now belong to the same company. Boot Barn acquired Sheplers in 2015 and bought Country Outfitter’s assets in 2017, so some of what looks like competition is one retailer running several brands.
Boot Barn
Boot Barn embodies the idea of the American West. Founded in 1978, it is now the largest country wear retailer in the US, currently operating more than 575 stores nationwide.
The brand focuses on supporting local communities and offers “a piece of the American spirit”. This is done through its numerous product ranges targeting American cowboys, workers, outdoorsmen, adrenaline junkies, and fashion enthusiasts.
In fiscal 2022, Boot Barn’s net sales grew by $594.8 million to a record $1.488 billion, according to its annual report. This could be due to a surge of backlogged consumer demand, pent up by the pandemic stay-at-home order. Lockdowns were followed by two years’ worth of demand being released over the course of one year.
We can see the limited demand for country wear by looking at Google Trends for 2020 below. The growth nearly doubled in 2021, accounting for the previous year’s decline.
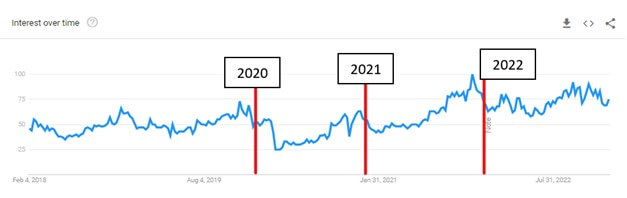
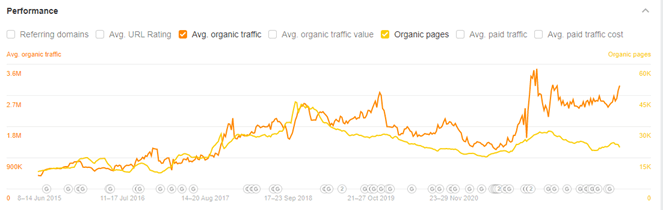
Let’s look at Boot Barn’s organic traffic using Ahrefs. Organic traffic somewhat correlates to the number of organic pages. However, we can assume the trends and seasonality in search volume are a more significant contributing factor, as Boot Barn’s organic traffic trends are relatively similar.
The organic traffic for the 2020 Christmas peak doesn’t reach similar levels, and the following 2021 peak is much greater. We can put this down to uncertainty around pandemic lockdowns in the US.
Boot Barn has also dabbled in paid traffic, but its effect on organic traffic seems minimal.
Sheplers
Founded in 1899 as a saddle store, Sheplers, along with its 25 locations, was acquired by Boot Barn in 2015. Its product range has since changed, now offering cowboy boots for western wedding attire.
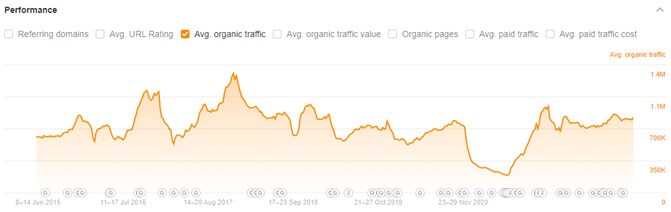
The pandemic hit Sheplers, like other competitors. However, it only sped up a decline that started in December 2017 and took organic traffic to an eight-year low.
Paid traffic leading up to this negative trend played a significant role. The injection of paid traffic started in 2015 when Boot Barn acquired Sheplers. One possible explanation is that Boot Barn invested in paid media for Sheplers after acquiring it. However, since this stopped in 2017, Sheplers’ organic traffic has continually declined.
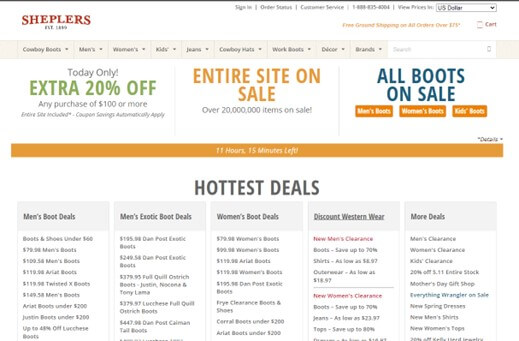
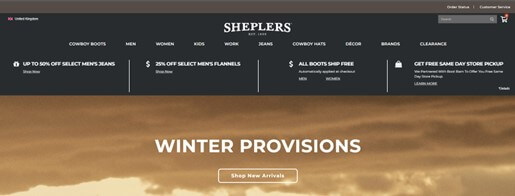
Using the Wayback Machine, we can compare Sheplers’ website from then to today. There are drastic differences in the overall website, suggesting there have also been changes to their SEO practices.
Ownership offers another possible explanation. With Sheplers and Boot Barn under one company, there’s little reason to fund two sites competing for the same keywords. The decline may reflect demand being consolidated onto bootbarn.com rather than lost.
At the moment, organic traffic remains stagnant. It has remained close to 826,000 since March 2022 and has shown little change since we passed the December peak. However, this doesn’t suggest an issue, because Google Trends remains relatively stagnant compared to previous years.
In previous years, Sheplers dabbled in paid traffic, but this has gradually become less common and isn’t significant enough to account for any recent organic traffic changes. Looking at organic keywords by top positions paints a relatively similar picture to organic traffic.
Country Outfitter
Country Outfitter was founded by an ex-physician and an ex-lawyer who, by their own account, had never worn a pair of cowboy boots. According to co-founder John James, it reached a $100 million annual revenue run rate within about six months of its first Facebook giveaway in September 2012.
With robotic warehousing and its own e-commerce platform, Country Outfitter became a key player in a competitive industry.
Country Outfitter found its initial success leveraging Facebook marketing, its internal e-commerce software, and internal warehouse management software. Doing so took revenue from $100,000 a month to $14.5 million a month just six months later.
This was when Facebook’s ad platform was still in its infancy, so there was less competition for ads. Consequently, bids were lower, and it was much more profitable than it is today.
Search alone couldn’t have built the business, as the numbers show. There were around 135,000 Google searches a month for cowboy boots, but Facebook let Country Outfitter reach 18.2 million people interested in country music, horses, and rodeo. Search harvested existing demand, while Facebook created new demand.
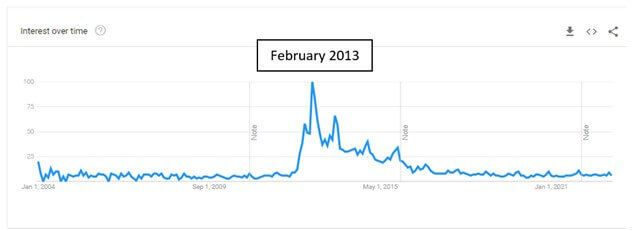
Country Outfitter has since seen a decline in performance. We can see this by looking at Google Trends, as shown below.
The founder points to several causes: Amazon and Zappos entering the category, brands selling direct, Facebook cutting organic reach from around 56% to under 1%, and a platform migration that dropped conversion rates by 38%. Boot Barn then bought the brand’s assets in 2017.
Looking at more recent metrics, we can see Country Outfitter no longer relies on paid traffic, likely because Google Ads is much more expensive than it was.
Since June 2021, we’ve seen an increase in organic pages and referring domains. That could indicate a new SEO strategy implementation – one that would have come from Boot Barn, which has owned the brand since 2017.
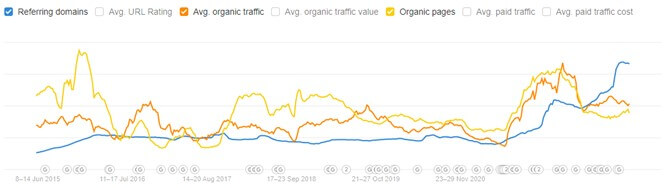
However, looking at the average organic traffic alone shows a relatively similar trend to the other competitors analysed – a gradual decline in traffic thanks to lockdowns, followed by an increase in traffic after restrictions were lifted.
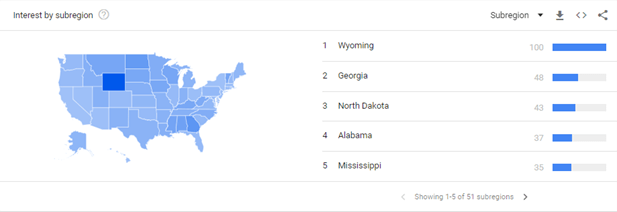
Most traffic for the search term “country outfitter” comes from Wyoming. This is an important note because the following dramatic increase in organic traffic occurred after Governor Gordon announced a full state reopening on 16 March 2021.
Cavender’s
Cavender’s, a family-run business founded in 1965 and named the top retailer in the US multiple times, has an extensive history in cowboy culture. From reselling in 1970 to the Urban Cowboy craze of the 1980s, when it comes to cowboy boots, they are a dominant force in the industry.
Average organic traffic shows a very similar trend to Sheplers. This could point to a greater cause for the 2018 peak than paid traffic. Cavender’s organic traffic peaks in December each year, but only managed to make a new high in December 2021. Similar to other competitors, this will likely be because Cavender’s products are purchased for Christmas presents.
However, traffic now remains somewhat stagnant. This could be due to the build-up and release of demand over the previous years. Having such high traffic during 2021 means less pent-up demand was left in the market. This pattern of organic traffic aligns with Google Trends data, suggesting it’s normal market behaviour and not an SEO issue.
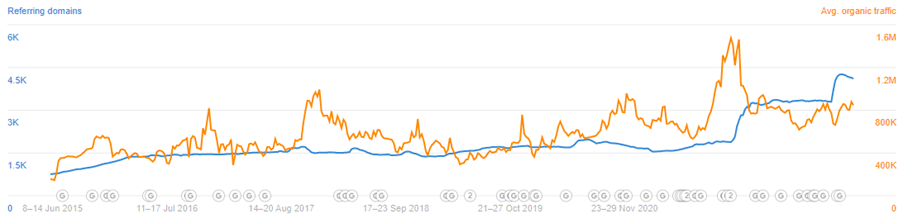
Cavender’s referring domains rose from November 2021 and kept climbing after traffic returned to normal levels. That pattern could reflect a sustained link-building strategy, not just a side effect of higher traffic: if the new links were simply earned through greater visibility, growth would have slowed when traffic did.
Buckle
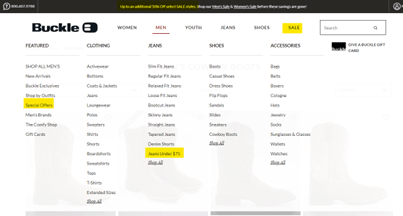
Buckle, like other competitors, also offers cowboy boots. However, cowboy boots only make up a small part of its product range. As its most expensive cowboy boot was $229.95 when we checked, it’s clear they target a different market. This is reflected in their header and menu options, shown below.
Placing a focus on price point and range, Buckle targets the mass market instead of a niche persona. This strategy has served them well. Growing from a single store in Nebraska in 1948, Buckle is now listed on the New York Stock Exchange (NYSE: BKE) with around 440 retail stores across the US.
Buckle’s average organic traffic is very similar to its competitors, with yearly highs in December, a decrease in traffic from December 2017 onward, followed by a new five-year high in December 2021. However, the organic traffic has continued to grow, even creating a new high in August 2022 and January 2023.
The increase points to the implementation of a good SEO strategy. We can partly rule out other marketing campaigns because the search volume for “buckle” has reduced drastically. If this surge in traffic were from another marketing campaign, it would likely cause an increase in branded search volume as well.
Buckle’s broader range likely contributes to this. Selling far more than western wear gives it a much wider set of non-branded keywords to rank for. This is exactly the long-tail opportunity the industry-wide keyword data pointed to.
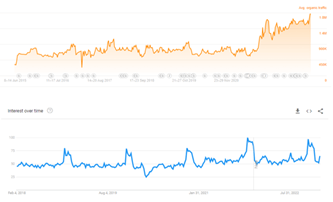
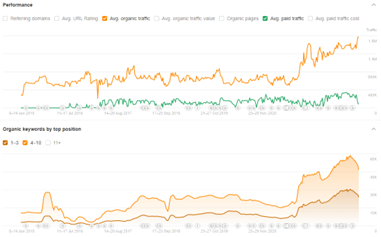
Some might argue it’s down to an increase in paid media. However, this is minimal, and we can see organic traffic continues to grow once paid media declines.
We can also look at organic keywords by position and see there has been a dramatic increase in 1-3 and 4-10 ranking keywords, providing further evidence it is the result of SEO.
Why the store will win country wear search
The wider market is tough for specialist retailers. As the Country Outfitter section showed, it’s becoming harder to compete with Amazon and Walmart, and ultimately this may be a losing game.
However, the retailers analysed here have the competitive advantage of being deeply rooted in American history and culture, meaning consumers are likely to still want to try their products before they buy.
That’s why the local search update matters so much. Looking at its impact across this collection of competitors, local SEO should be a core part of any SEO strategy in the industry.
Customers still want to try on clothes and boots before they buy, so the customer journey will involve searching for local stores. Retailers can still have a competitive advantage over online giants using SEO.
In country wear, organic search wins when it sends people to the store, not just the checkout. Retailers with the most stores can gain the most from getting local search right.
Across the five retailers, the data tells a consistent story:
- Boot Barn leads the market – its sales tracked the 2021 demand peak.
- Sheplers has declined since 2017 – possibly as Boot Barn consolidates demand onto its own site.
- Country Outfitter shows that paid social can build a brand fast – but it can’t keep one there.
- Cavender’s traffic is flat – rising referring domains suggest investment ahead of the next peak.
- Buckle is the strongest organic performer – it’s helped by a broad product range and targeting a wide range of long-tail keywords.
Want to know how your stores show up when shoppers search locally, or where your category’s long-tail demand is unclaimed? Talk to us about enterprise local SEO and building a strategy around how your customers actually search for and buy products within your industry.


